01The numerator is never the problem
The P/E is a division: share price over earnings per share. The price is public, everyone sees the same one, and it admits no interpretation. So when two sources disagree, the disagreement is always underneath, in the earnings.
And there are at least three different earnings figures circulating for the same company:
- Reported (GAAP in the United States, IFRS in Europe): what the company files with its regulator and a third party audits. It includes everything: impairments, severance, litigation, the cost of paying employees in shares.
- Adjusted, or non-GAAP: the same earnings minus whatever the company considers extraordinary. Each company defines it, and no two define it the same way.
- Estimated: what analysts expect next year. That one produces the forward P/E, which is a different thing again.
02How much it changes
Take a mid-sized company at €50 a share, 200 million shares, reported net income of €250M and a €60M charge the company treats as one-off. Reported EPS is €1.25 and the P/E is 40. Add the charge back and adjusted EPS becomes €1.55, which puts the P/E at 32.3.
The company has not changed. The denominator has. The same stock appears 19% cheaper on one site than on the other, and that is the number a lot of people use to decide whether something is expensive.
Move the numbers yourself in the P/E calculator →
And there is a case where the P/E stops meaning anything at all: negative earnings. A P/E of −8 does not mean «cheap». It means the company is losing money and the ratio does not apply. Tools that print a negative number there are reporting something that cannot be interpreted.
03Where the real error creeps in
The serious problem is not choosing badly: it is mixing. It happens when a tool takes earnings from one source and the analyst consensus from another, and the two are not talking about the same figure.
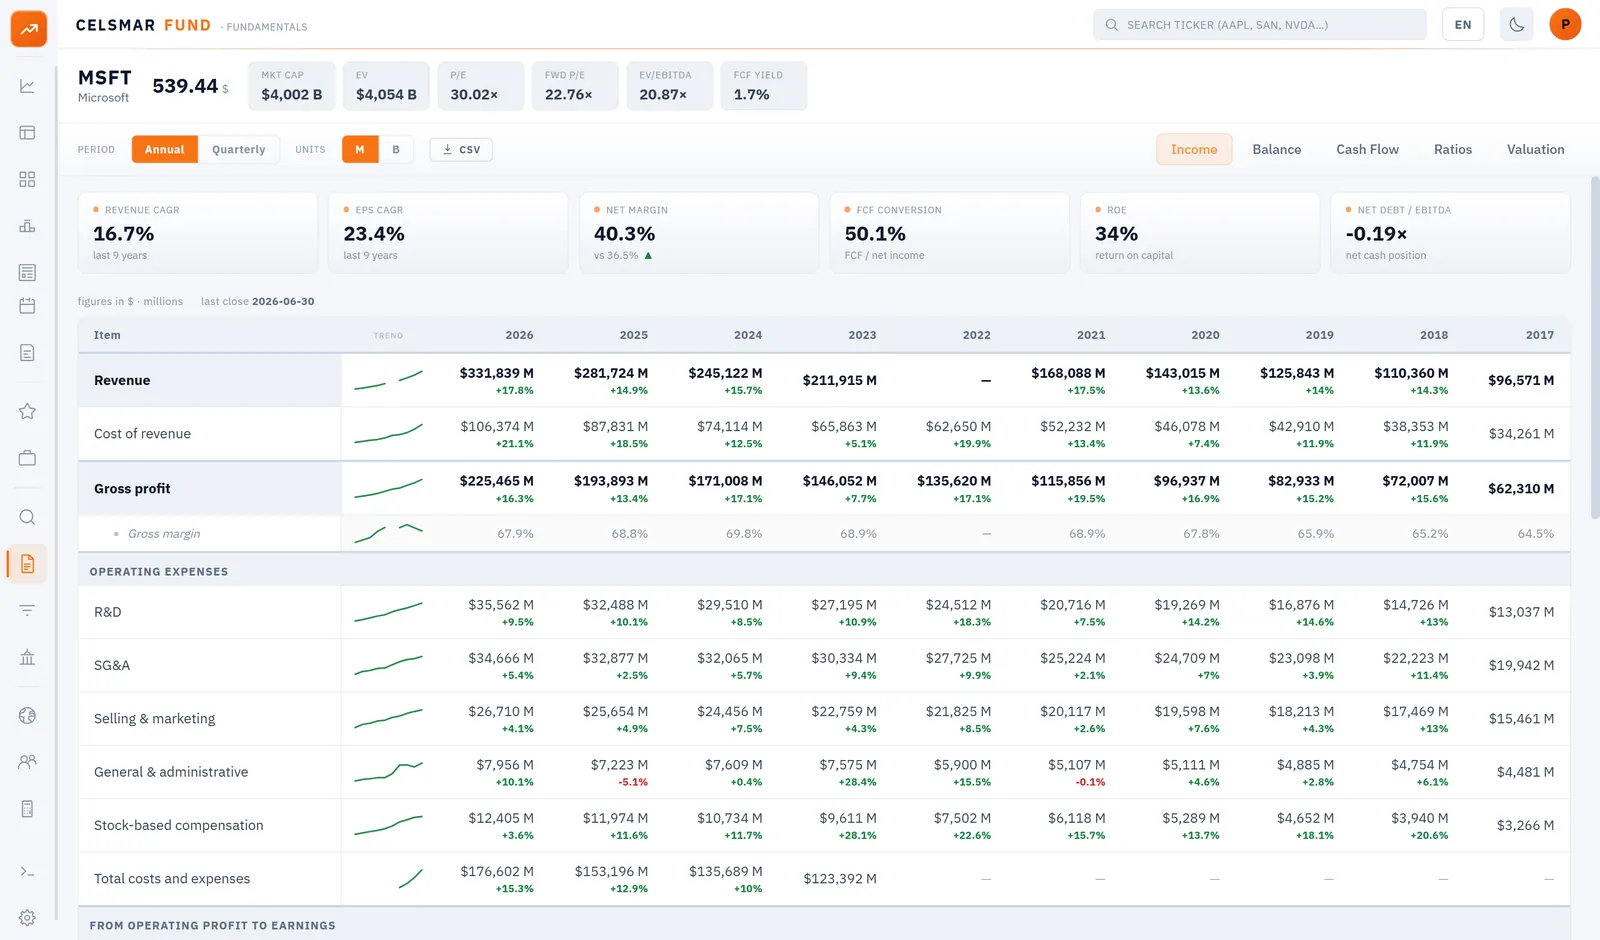
That is exactly what we guard against in our own data: the earnings per share shown in the history is governed by the company's own filing, not by the adjusted figure that earnings-surprise providers publish. Compare reported earnings against a consensus built on adjusted ones and the surprise you compute is artificial: you get a miss where there was none, or a beat that never happened.
The second trap is the period. A trailing twelve-month P/E uses four consecutive quarters. If one is missing from the series, some providers fill it with the same quarter a year earlier and keep calling it TTM. At that point the figure is not twelve months of anything.
04How to tell what you are looking at
- Look for the label. A serious tool says whether the P/E is reported or adjusted, and for which period. If it does not say, you do not know, and if you do not know, you cannot compare.
- Compare like with like. If you are comparing two companies, take both from the same source on the same basis. An adjusted P/E of 18 against a reported 26 is not a comparison, it is a coincidence.
- Look at both. The gap between reported and adjusted is information in itself: when a company excludes «extraordinary» charges every single year, those charges are fairly ordinary.
- Distrust a P/E with no earnings in sight. If you cannot see the earnings it came from, you are trusting a division you cannot redo.
Frequently asked questions
What is the difference between GAAP and non-GAAP earnings?
GAAP earnings (IFRS in Europe) are what the company files with its regulator and an auditor signs off. Non-GAAP, or adjusted, earnings are the same figure with items the company considers extraordinary added back: impairments, restructuring, litigation, share-based pay. Non-GAAP is not regulated, each company decides what it excludes, and it almost always produces a higher earnings figure and therefore a lower P/E.
Why do two websites show a different P/E for the same stock?
Because they are not dividing by the same earnings. One uses reported GAAP or IFRS earnings and the other the company's adjusted figure, and the gap can easily be 20%. The period matters too: trailing twelve months, last closed financial year and next-year estimate give three different P/E ratios on the same day. Neither site is necessarily wrong; what is usually missing is a statement of which basis they used.
Is a negative P/E ratio meaningful?
No. There is no such thing as a multiple of a loss, so with negative earnings the ratio should be left blank or marked as not applicable. A P/E of −8 does not mean the stock is cheap; it means the formula makes no sense with that denominator. For loss-making companies, EV/sales or EV/EBITDA are used instead when EBITDA is positive.
Which P/E should I use, reported or adjusted?
Both, and consistently. Reported earnings are auditable and comparable across companies; adjusted earnings can be closer to the underlying business when the exclusions are genuinely one-off. The useful signal is the gap between them: a company that excludes extraordinary charges every year is telling you those charges are ordinary. What you cannot do is compare an adjusted P/E for one company against a reported one for another.
The earnings per share shown in Celsmar's history is governed by the company's own filing rather than by third-party adjusted figures, precisely so that reported earnings are never compared against an adjusted consensus.
This is information and analysis, not financial advice, and it contains no recommendation to buy or sell. See the disclaimer.