Operating margin
Operating margin is the percentage of sales left as profit after operating costs, before interest and taxes. It measures the efficiency of the business itself, and its trend over the years says more about a company's health than its absolute level in any single year: a margin that narrows year after year is a warning sign even while it stays high.
How it is calculated
Operating margin = EBIT ÷ revenue. With €1,000M of sales and EBIT of €150M, the margin is 15 %: of every €100 invoiced, 15 remain after cost of sales, staff, rent and depreciation, and before interest and tax. It stops at that point deliberately, because it measures the business and not how it is financed: two identical companies with different debt have the same operating margin and different net margin. What informs is not the level but the trend and the comparison with its own sector: 15 % is excellent in distribution and mediocre in software.
The figures in the example are invented and rounded so the arithmetic can be redone by hand. They are not data from any real company.
What it is not
It is not gross margin, which only deducts the direct cost of what was sold and is always higher. Nor is it net margin, which comes after interest and tax. And distrust an impossible operating margin: above 100 % it is arithmetically absurd barring an error, and it usually comes from mixing the EBIT of a consolidated statement with the revenue of a standalone one, or two generations of restated accounts in the same row.
In the terminal
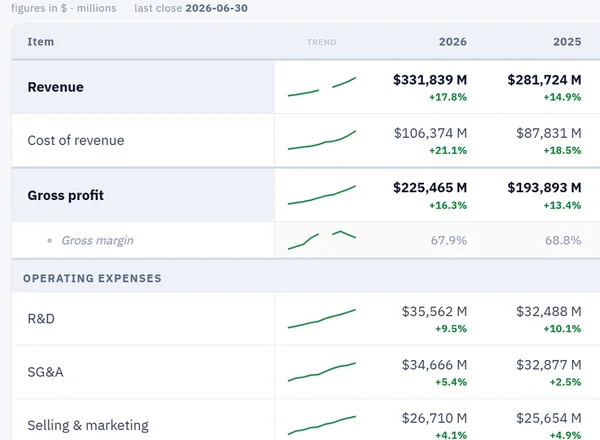
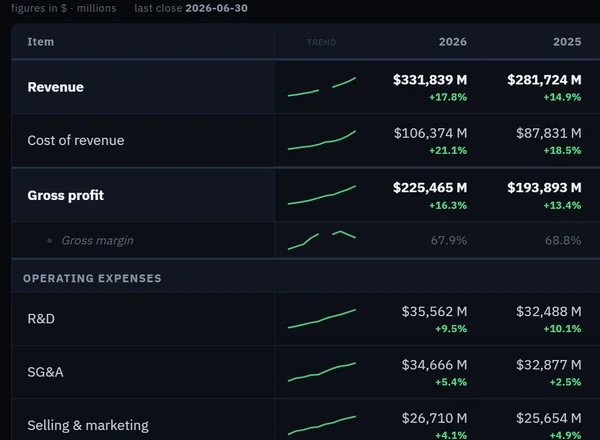
Income statement, balance sheet and cash flows by fiscal year or quarter, with the change in every line and its trend.
See the full glossary · What the Celsmar financial terminal is
Definition for informational purposes. It is not financial advice nor a recommendation to buy or sell.